Protocol
How withholding is engineered, reported and re-routed through the nominee structure.
The Nominee Withholding Disconnect explains how corporate surplus, backup withholding, and IRS reporting mechanisms interact within the nominee framework, and how these processes can be challenged, verified, and corrected.
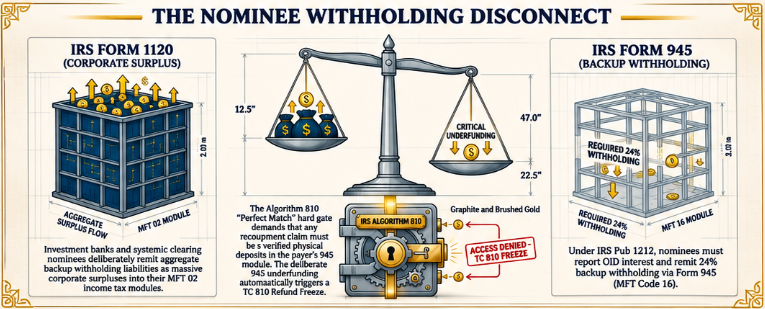
How backing withholding is aggregated and reported through the corporate surplus framework.
The required 24% withholding and its role within the nominee reporting structure.
The “Perfect Match” gate, how it operates, and why underfunding triggers a TC 810 refund freeze.
How to identify the withholding disconnect and the key steps to challenge and restore the proper position.
This chapter examines the relationship between IRS Form 1120, Form 945, and Algorithm 810, and how the nominee structure is used to manage the flow of corporate surplus and withholding. It sets out the key mechanisms that create the withholding disconnect, the impact on your reporting position, and the steps required to verify, challenge, and correct the process.
Get the full PDF delivered instantly to your inbox.
Select what you want to download.