Protocol
The framework for recognising and establishing your standing as a Holder in Due Course (HDC).
Establishing Holder in Due Course Standing sets out the legal and administrative framework that recognises the trust’s rights to the original negotiable instrument, rebuts presumptions of ownership, and confirms the living individual as the true originator.
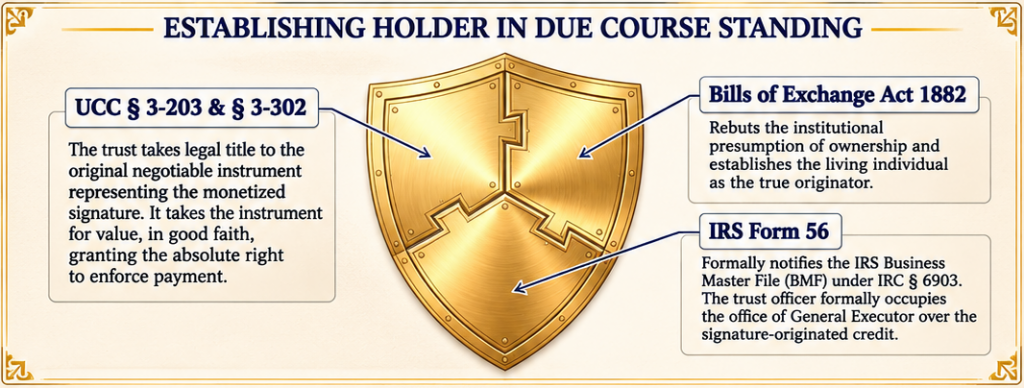
Provides the legal title and Holder in Due Course (HDC) standing to enforce the instrument.
Disproves the institutional presumption of ownership and confirms the living individual as the true originator.
Notifies the IRS BMF under IRC § 6903 and establishes the General Executor role over the signature-originated credit.
This chapter explains how Holder in Due Course (HDC) standing is established through the UCC, the Bills of Exchange Act, and IRS Form 56. It outlines how legal title, originator status, and the General Executor role work together to secure and enforce your position over the signature-originated credit.
Get the full PDF delivered instantly to your inbox.
Select what you want to download.