Protocol
Identifying and bypassing the key statutory thresholds that delay or obstruct the lawful processing of your claim.
Navigating Statutory Chokepoints explains the key thresholds, time delays and statutory review mechanisms that can interrupt or delay payment, and how to structure your claim to move through the system lawfully and efficiently.
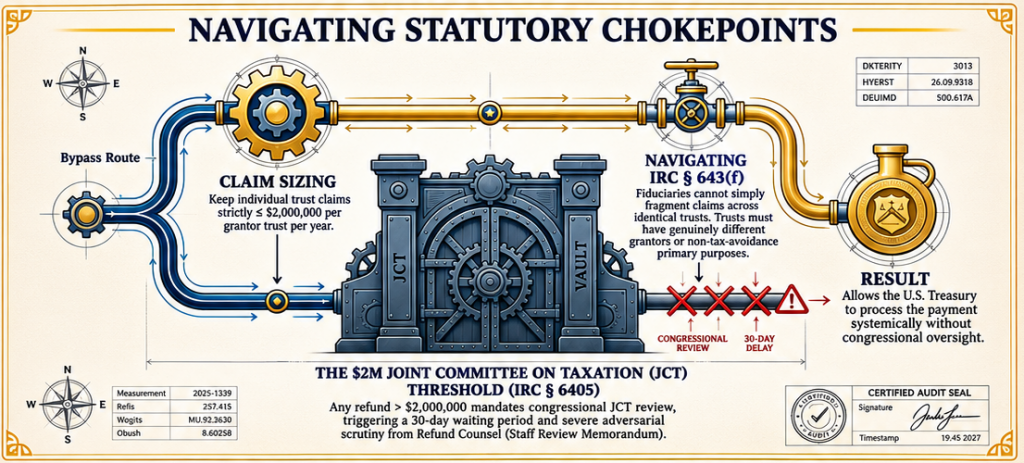
Keep individual trust claims strictly ≤ $2,000,000 per grantor trust per year.
Trusts must have genuinely different grantors or non-tax-avoidance primary purposes.
Any refund greater than $2,000,000 triggers Joint Committee on Taxation (JCT) review and a 30-day waiting period.
A properly structured claim allows the U.S. Treasury to process the payment systemically without congressional oversight.
This chapter shows how to identify and navigate the key statutory chokepoints that can delay or obstruct the processing of your claim, including the $2M JCT threshold (IRC § 6405) and the rules under IRC § 643(f). It sets out how proper claim sizing and trust structuring help avoid unnecessary review, reduce delays, and keep your claim moving lawfully through the system.
Get the full PDF delivered instantly to your inbox.
Select what you want to download.