Protocol
The process to correct, report and reset the 1099-OID through the proper fiduciary and administrative framework.
The Corrective 1099-OID Administrative Reset explains how to rectify the improper reporting of Original Issue Discount (OID) interest, ensure the correct identification of the beneficial owner, and reset the administrative record through the appropriate fiduciary filings.
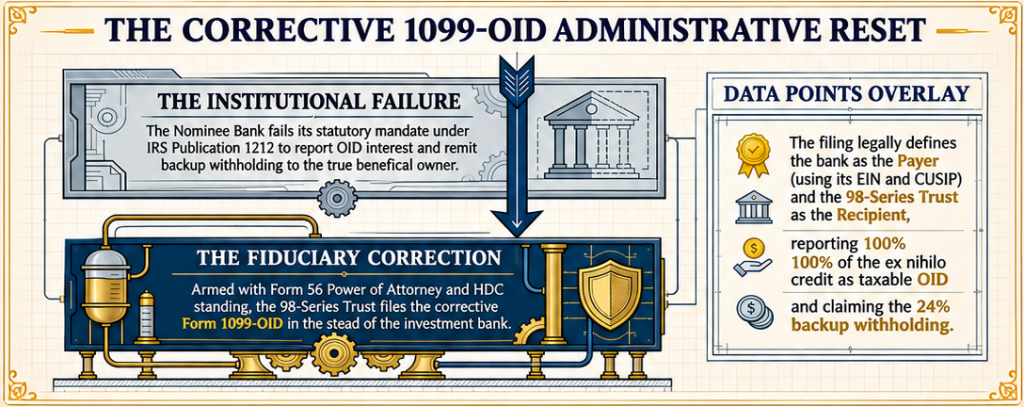
How the nominee bank fails to report OID interest and remit backup withholding under IRS Publication 1212.
How Form 56 and HDC standing enable the 98-Series Trust to file the corrective Form 1099-OID.
How the filing correctly identifies the bank as the Payer and the 98-Series Trust as the Recipient.
How 100% of the ex nihilo credit is reported as taxable OID and the 24% backup withholding is claimed.
This chapter outlines the steps to correct the improper handling of Original Issue Discount (OID) through the use of Form 56, Holder in Due Course (HDC) standing, and a corrective Form 1099-OID. It explains how the filing resets the administrative record, ensures the proper identification of the Payer and Recipient, and addresses the reporting of OID and the 24% backup withholding.
Get the full PDF delivered instantly to your inbox.
Select what you want to download.